
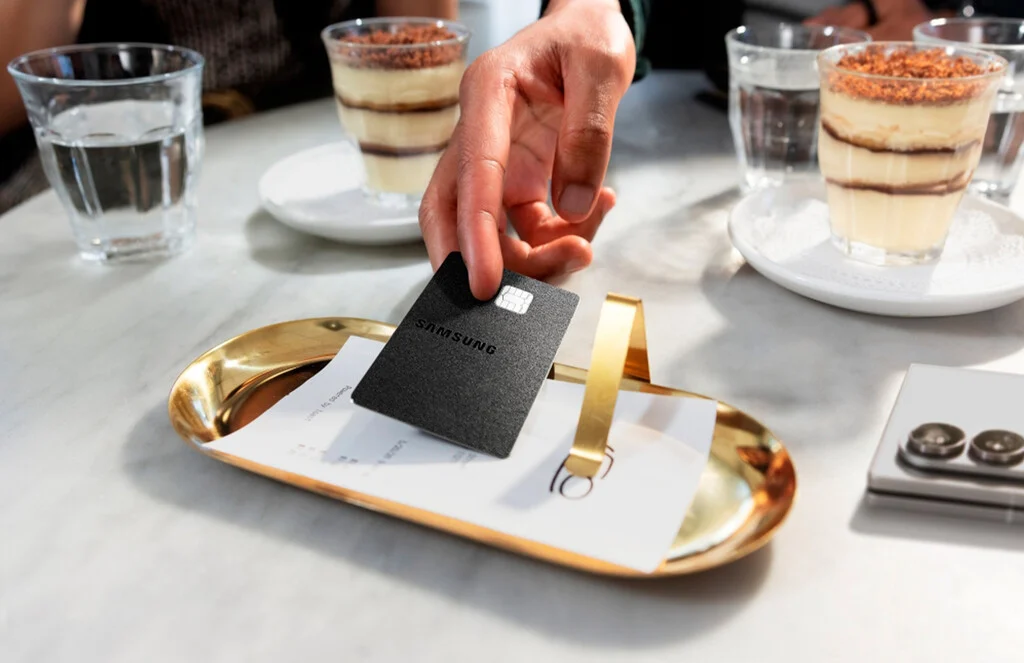

Samsung Electronics America has officially introduced the Samsung Galaxy Card, marking a significant expansion of its financial services portfolio and a deepened commitment to its vast ecosystem. This new credit card offers users an innovative way to earn cashback on everyday purchases, with enhanced rewards specifically for transactions made within the Samsung brand. Launched on July 22, 2026, the Galaxy Card represents Samsung’s inaugural foray into the credit card market, aiming to provide a comprehensive financial tool that integrates seamlessly with the brand’s digital environment.
The introduction of the Samsung Galaxy Card is not merely about offering another payment method; it’s a strategic initiative designed to bolster customer loyalty, enhance the utility of the Samsung Wallet, and create a more interconnected experience for Galaxy users. It positions Samsung as a holistic lifestyle brand, extending its influence beyond consumer electronics into the realm of personal finance.
A Premium Design Meets Lucrative Rewards
The Samsung Galaxy Card is issued by Barclays US Consumer Bank and operates on the robust Visa network, ensuring wide acceptance globally. From its launch date, consumers have been able to apply for the card, which comes with an attractive welcome bonus: a $200 statement credit for new cardholders who spend $2,000 or more within the first 90 days of account opening. This introductory offer is designed to incentivize early adoption and reward initial spending, setting a competitive tone in the co-branded credit card market.
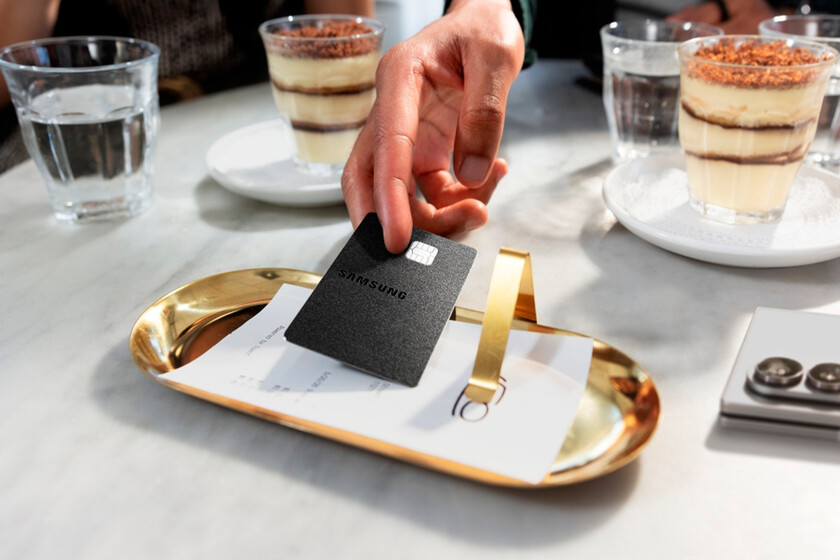
Beyond its financial incentives, the Galaxy Card distinguishes itself with its aesthetic and tactile appeal. It will be available in both virtual format, for immediate use within Samsung Wallet, and as an elegant physical card crafted from premium metal, emblazoned with the distinctive Samsung logo in black. This design choice aligns with a growing trend among premium credit cards, where the physical card itself becomes a statement of exclusivity and sophistication, reflecting the high-end nature of Samsung’s flagship devices.
However, a notable limitation at launch is its exclusivity to the United States market. While this is a common strategy for new product rollouts, particularly in regulated financial sectors, it underscores Samsung’s initial focus on its largest market before potential global expansion.
The reward structure is engineered to maximize value for Samsung loyalists while still providing competitive returns on general spending:
- Specific cashback percentages will be detailed upon full product launch, but the announcement highlights significantly higher rewards for purchases made directly with Samsung, encouraging customers to invest further in the Galaxy ecosystem.
- Everyday purchases will also yield competitive cashback rates, ensuring the card remains a viable primary payment option for a broad spectrum of consumer spending.
Woncheol Chai, Executive Vice President and Head of the Digital Wallet Team at Samsung’s MX Business, articulated the vision behind the card: “For years, users have relied on Samsung products to enhance their daily lives, whether for staying connected, relaxing, or being more productive. Today, the Samsung Galaxy Card offers a new way to earn rewards every time you pay. People lead busy lives and need a card that simplifies their life and provides real value; the Galaxy Card delivers on both.” This statement emphasizes the card’s dual purpose: convenience and tangible benefits for the modern consumer.
Integration into the Galaxy Ecosystem: The Heart of the Offering
The most compelling aspect of the Samsung Galaxy Card is its native and deep integration with Samsung Wallet. This synergy transforms the card from a mere payment tool into a central component of the broader Galaxy experience. Users can securely store the Galaxy Card alongside other compatible payment cards, digital identity documents, transit passes, digital keys for smart homes or vehicles, and loyalty programs within the Samsung Wallet app.
Samsung Wallet has evolved significantly from its origins as Samsung Pay, transforming into a comprehensive digital hub designed to consolidate and simplify various aspects of a user’s digital life. This platform aims to provide a single, secure repository for all essential digital credentials, reflecting a broader industry trend towards integrated digital wallets. The Galaxy Card’s presence within this ecosystem enhances its utility, allowing users to manage their finances, track rewards, and make payments with unparalleled ease and security directly from their Galaxy devices.
Security remains a paramount concern for any financial product, and Samsung has addressed this by integrating the Galaxy Card’s operations within Samsung Wallet with Samsung Knox. Samsung Knox is a multi-layered security platform built into Samsung devices, offering hardware-backed security features that protect sensitive data from malware, cyber threats, and unauthorized access. This enterprise-grade security ensures that personal and financial information associated with the Galaxy Card is safeguarded to the highest industry standards, providing users with peace of mind in an increasingly digital world. The open ecosystem approach of Samsung Wallet also suggests future growth with new partners, further expanding its utility and cementing its role as a central digital management tool.
Timeline and Background Context: Samsung’s Journey into Fintech
Samsung’s venture into financial services is not an overnight decision but rather a carefully orchestrated evolution spanning several years. The journey began in 2015 with the launch of Samsung Pay, a mobile payment service that utilized both Near Field Communication (NFC) and Magnetic Secure Transmission (MST) technologies, giving it a broader acceptance footprint compared to competitors like Apple Pay. This early success laid the groundwork for Samsung to understand consumer payment behaviors and build trust in its digital payment solutions.
Over time, Samsung Pay evolved into Samsung Wallet, a strategic rebranding that reflected an ambition to move beyond simple payments. Samsung Wallet began incorporating digital keys, IDs, and cryptocurrency management, signaling a broader intent to create a comprehensive digital identity and asset management platform. The introduction of the Galaxy Card in 2026 is a logical next step in this progression, leveraging the existing user base and infrastructure of Samsung Wallet to offer a branded financial product that directly rewards loyalty to the Samsung ecosystem.
This move also places Samsung in a competitive landscape alongside other tech giants. Apple, for instance, launched the Apple Card in partnership with Goldman Sachs in 2019, offering similar ecosystem integration and cashback rewards. Amazon has long had co-branded credit cards with partners like Chase, rewarding Prime members with significant cashback on Amazon purchases. These precedents demonstrate a clear trend: tech companies are increasingly seeking to deepen customer engagement and capture more transaction value by offering their own financial products, turning their vast user bases into captive markets for financial services.
Supporting Data and Market Implications
The global market for co-branded credit cards is substantial and growing, driven by consumers seeking value and loyalty rewards. According to various market analyses, co-branded cards often see higher engagement rates and lower churn compared to generic credit cards, precisely because they tap into existing brand loyalty. For Samsung, with hundreds of millions of Galaxy device users worldwide, the potential market for the Galaxy Card is immense. Data from Statista indicates that mobile payment adoption continues to rise steadily, with digital wallets becoming the preferred payment method for a significant portion of consumers. The Galaxy Card capitalizes on this trend by integrating directly into Samsung’s popular mobile wallet.
The partnership with Barclays US Consumer Bank is critical. Barclays brings extensive experience in credit card issuance, risk management, and regulatory compliance, areas where a technology company like Samsung would otherwise face steep learning curves. For Barclays, this partnership offers access to Samsung’s massive and engaged customer base, providing a significant opportunity to expand its cardholder portfolio and innovate in the digital banking space. Visa, as the network provider, ensures universal acceptance and leverages its robust infrastructure for secure transactions.
The implications of the Galaxy Card are multi-faceted:
- For Samsung: It strengthens brand stickiness. By offering tangible financial rewards for choosing Samsung products, the card creates an additional incentive for customers to remain within the Galaxy ecosystem, potentially increasing sales of devices, accessories, and services. It also opens new revenue streams through interchange fees and interest income (shared with Barclays).
- For Consumers: For Samsung loyalists, the card offers a compelling value proposition through tailored rewards and seamless integration. It simplifies financial management by centralizing payment and loyalty functions within Samsung Wallet. However, consumers should always evaluate the reward structure against their spending habits and be mindful of interest rates and fees, as with any credit product.
- For the Fintech and Banking Industry: The Galaxy Card intensifies competition, pushing traditional banks and other tech companies to innovate further in their loyalty programs and digital integration. It validates the model of embedding financial services directly into consumer technology platforms, signaling a future where more brands might follow suit. It also highlights the ongoing convergence of technology and finance, blurring the lines between these sectors.
Official Responses and Broader Outlook
While Woncheol Chai’s statement from Samsung provides the primary official commentary, the strategic importance of this launch would logically elicit positive responses from the partners involved. Barclays US Consumer Bank would likely emphasize the innovative nature of the partnership, its commitment to digital financial solutions, and the opportunity to serve a tech-savvy customer segment. Visa would highlight its role in enabling secure, seamless transactions and its dedication to fostering innovation in the payment ecosystem. These partnerships are not just transactional; they are strategic alliances that leverage the strengths of each entity to create a robust new offering.
The current exclusivity to the U.S. market is a typical phased rollout strategy, allowing Samsung and Barclays to fine-tune the product, gather user feedback, and navigate regulatory complexities in a single, large market before contemplating broader expansion. The U.S. market is highly competitive but also mature in terms of credit card adoption and digital payment usage, making it an ideal testing ground. If successful, it is highly probable that Samsung will explore bringing the Galaxy Card to other key markets where its brand presence is strong and digital payment adoption is high, such as South Korea, Europe, and India. Such expansion would require new partnerships with local banks and adherence to diverse regulatory frameworks.
Conclusion
The Samsung Galaxy Card is more than just a new credit card; it is a declaration of Samsung’s ambition to be an indispensable part of its users’ digital and financial lives. By combining a premium design, attractive cashback rewards, and deep integration with the secure Samsung Wallet ecosystem, the company is making a compelling case for brand loyalty. This initiative represents a significant step in the ongoing convergence of technology and financial services, setting a new benchmark for how tech giants can leverage their platforms to offer value and convenience to their customers. As the financial landscape continues to evolve, the Galaxy Card positions Samsung at the forefront of this transformation, ready to capitalize on the growing demand for integrated, digitally-native financial solutions. The industry will be watching closely to see how this strategic move impacts consumer behavior and shapes the future of co-branded financial products globally.
