

The telecommunications sector in the Lao People’s Democratic Republic (Lao PDR) has undergone a period of unprecedented acceleration, transitioning from a nascent market to a robust digital ecosystem characterized by more than 10 million mobile subscribers as of recent reporting cycles. This surge represents a significant milestone for a landlocked nation of approximately 7.5 million people, indicating a mobile penetration rate that exceeds 130%—a phenomenon driven by the common practice of consumers maintaining multiple SIM cards to navigate varying network strengths and promotional offers. Currently, the industry is defined by the strategic maneuvers of four primary mobile service providers: Unitel, Lao Telecom (LaoTel), TPlus Laos, and ETL Laos. These entities are not only competing for market dominance through pricing and technology but are also serving as the backbone for the nation’s broader digital "Lao 4.0" strategy, which seeks to integrate telecommunications into every facet of the national economy, from rural agriculture to urban fintech solutions.
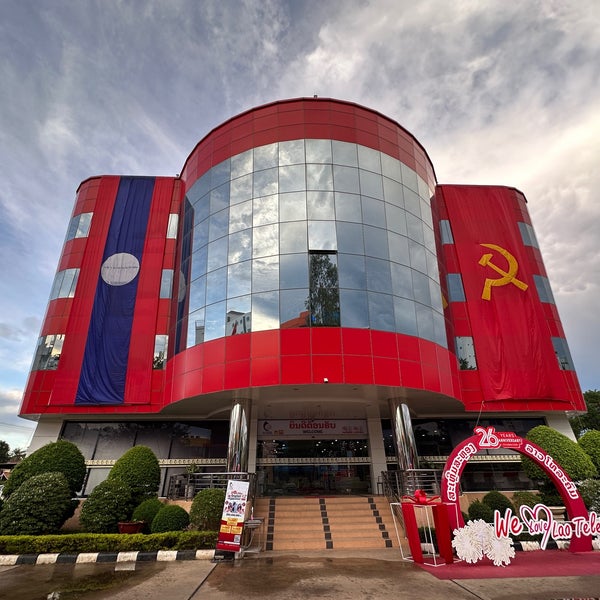
The evolution of the Lao mobile market is a narrative of strategic foreign investment and state-directed development. The timeline of this sector began in earnest in 1996 with the establishment of Lao Telecom, a joint venture between the Lao government and Shenington Investments (a subsidiary of Thailand’s Thaicom). For over a decade, the market remained relatively consolidated until 2008, when the entry of Unitel—a joint venture between the Lao Ministry of Defense’s Lao Asia Telecom and Vietnam’s military-run industry giant Viettel—fundamentally disrupted the landscape. Unitel’s aggressive infrastructure deployment, particularly in remote and mountainous regions that were previously underserved, allowed it to rapidly overtake the incumbent. In 2009, the market diversified further with the entry of VimpelCom (operating under the Beeline brand, now TPlus), followed by the restructuring of the Enterprise of Telecommunications Lao (ETL) into a joint venture with Chinese investors in 2015. This chronological progression highlights a shift from a monopoly-style environment to a competitive multi-player market that balances state interests with international technical expertise.
Market share data as of the most recent comprehensive fiscal assessments indicates a clear hierarchy within the industry. Unitel maintains a commanding lead with approximately 51% of the total market share, leveraging its extensive rural network to secure over 5 million subscribers. Lao Telecom follows as a strong second with a 34% share, maintaining a loyal base of 3 million subscribers, particularly among government institutions and urban professionals. TPlus Laos holds roughly 10% of the market, positioning itself as a lifestyle brand for the youth demographic, while ETL Laos occupies the remaining 5%. This distribution reflects the varying capital investment capabilities of each firm, with Unitel and LaoTel benefiting from substantial infrastructure legacies and state-backed support.
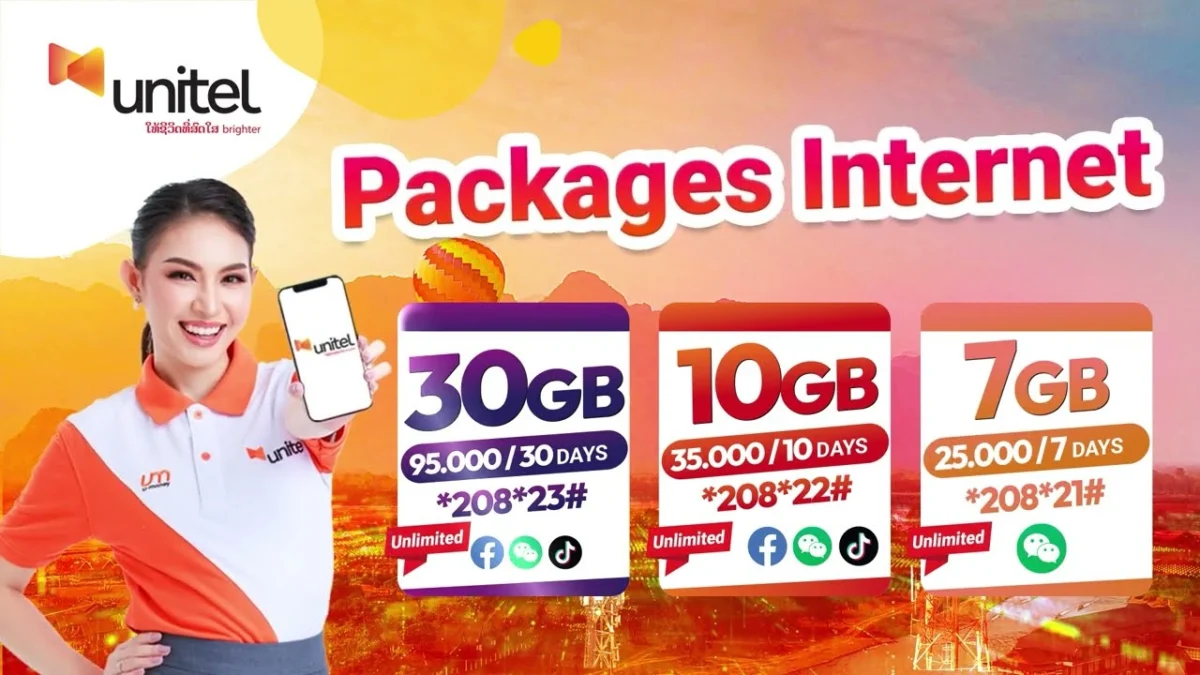
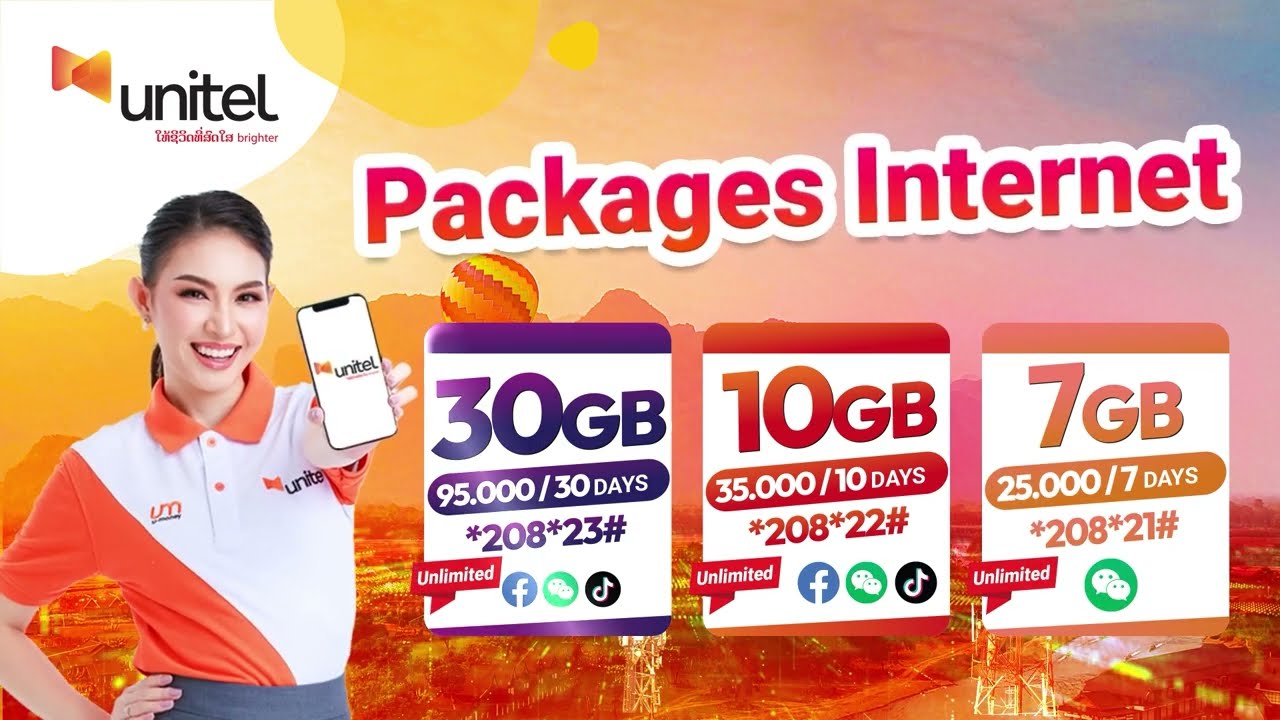
Unitel’s dominance is largely attributed to its "localized" strategy. By mirroring the business model of its parent company, Viettel, Unitel focused on the "bottom of the pyramid," ensuring that even the most isolated villages in provinces like Phongsaly or Attapeu had access to basic voice and data services. Beyond traditional connectivity, Unitel has pioneered value-added services (VAS) including the "U-money" mobile wallet, which has become a critical tool for financial inclusion in a country where traditional banking penetration remains low. Similarly, Lao Telecom has maintained its relevance by focusing on high-end technological shifts. It was the first operator to pilot 5G technology in Vientiane, signaling its intent to capture the high-value enterprise and industrial sectors as Laos seeks to modernize its manufacturing and logistics hubs along the new China-Laos Railway corridor.
The service portfolios of these operators have expanded far beyond simple SMS and voice calls. In the current market, data is the primary commodity. The average cost of mobile data in Laos is notably competitive within the ASEAN region, with 1GB of data typically priced between $2 and $5 USD depending on the validity period and bundle type. This affordability has been a catalyst for the explosion of social media usage and the growth of local e-commerce. A significant recent innovation in the service sector is the introduction of eSIM technology, specifically targeted at the tourism industry. With the post-pandemic recovery of the tourism sector—a vital pillar of the Lao economy—operators have streamlined the process for international visitors to acquire connectivity. Through platforms like laosesim.com and authorized retail outlets, tourists can now activate local profiles on their devices before even clearing customs, bypassing the logistical hurdles of physical SIM cards and contributing to a more seamless travel experience.
Technologically, the Lao mobile landscape is in a state of transition. While the Global System for Mobile Communications (GSM) remains the foundational standard for voice services, the deployment of 4G LTE has reached near-ubiquity in urban centers and provincial capitals. The current strategic focus has shifted toward 5G. The Lao government, through the Ministry of Post and Telecommunications, has expressed a clear mandate to adopt 5G to support the "Smart City" initiatives in Vientiane and the Luang Prabang Special Economic Zone. However, the transition to 5G presents a significant financial challenge. The capital expenditure required for 5G infrastructure is immense, and operators must balance these investments against the relatively low Average Revenue Per User (ARPU) characteristic of the Lao market.
The regulatory environment, managed by the Ministry of Post and Telecommunications (MPT), has become increasingly sophisticated. The MPT is tasked with the dual role of fostering competition while ensuring national security and consumer protection. Recent regulatory trends include stricter requirements for SIM card registration to combat telecommunications fraud and the implementation of price floors to prevent predatory pricing that could destabilize the smaller operators. Industry analysts suggest that while these regulations add a layer of bureaucratic complexity, they are essential for creating a "level playing field" in a market where two players control 85% of the traffic.
Despite the rapid growth, several structural challenges persist. The primary obstacle is the country’s geography. Laos is approximately 70% mountainous, which makes the cost of laying fiber-optic backhaul and maintaining cell towers in remote areas prohibitively expensive. This has resulted in a "digital divide" where urban users enjoy high-speed 4G/5G connectivity, while rural populations may still struggle with inconsistent 3G signals. Furthermore, there is a noted shortage of high-level local technical talent, forcing many operators to rely on expatriate engineers from Vietnam, Thailand, and China. Addressing this skills gap is a priority for the government, which is currently working with mobile operators to establish vocational training programs focused on telecommunications engineering and cybersecurity.
The future outlook for the Lao mobile market is inextricably linked to the country’s integration into the regional digital economy. The completion of the China-Laos Railway and the development of various economic zones are expected to drive demand for high-capacity industrial IoT (Internet of Things) applications and logistics tracking services. This provides a lucrative opportunity for operators to diversify their revenue streams away from consumer mobile plans and toward B2B (business-to-business) solutions. Additionally, the convergence of telecommunications and finance (FinTech) is expected to accelerate. As more Lao citizens gain access to smartphones, the mobile phone will likely become the primary vehicle for all financial transactions, including utility payments, remittances, and micro-loans.
Customer satisfaction metrics provide a nuanced view of the industry’s performance. Surveys conducted by regional consumer advocacy groups and tourism institutes indicate high levels of satisfaction regarding the ease of access and the affordability of data. However, there are lingering concerns regarding network congestion in Vientiane during peak hours and the lack of responsive customer support in minority languages in rural provinces. The "tourist experience" has seen the most significant improvement, with the digital-first approach to eSIMs and international roaming packages receiving positive feedback from Western and regional travelers alike.
In conclusion, the mobile telecommunications sector in Laos has evolved from a basic utility into a sophisticated engine of socio-economic development. While Unitel and Lao Telecom continue to lead the market, the presence of TPlus and ETL ensures a competitive environment that benefits the consumer through lower prices and innovative services. The challenges of infrastructure and human capital remain, but the trajectory is clear: Laos is aggressively pursuing a digital future. As the nation prepares for the next wave of technological integration, the role of mobile operators will be more than just providing a signal; they will be the architects of the country’s digital identity in an increasingly connected Southeast Asia. The ongoing investment in 5G, the expansion of rural connectivity, and the rise of mobile financial services suggest that the Lao telecommunications story is only in its opening chapters, with significant growth and transformation yet to come.
